Nashville, TN Industrial Market Report Q2 2026
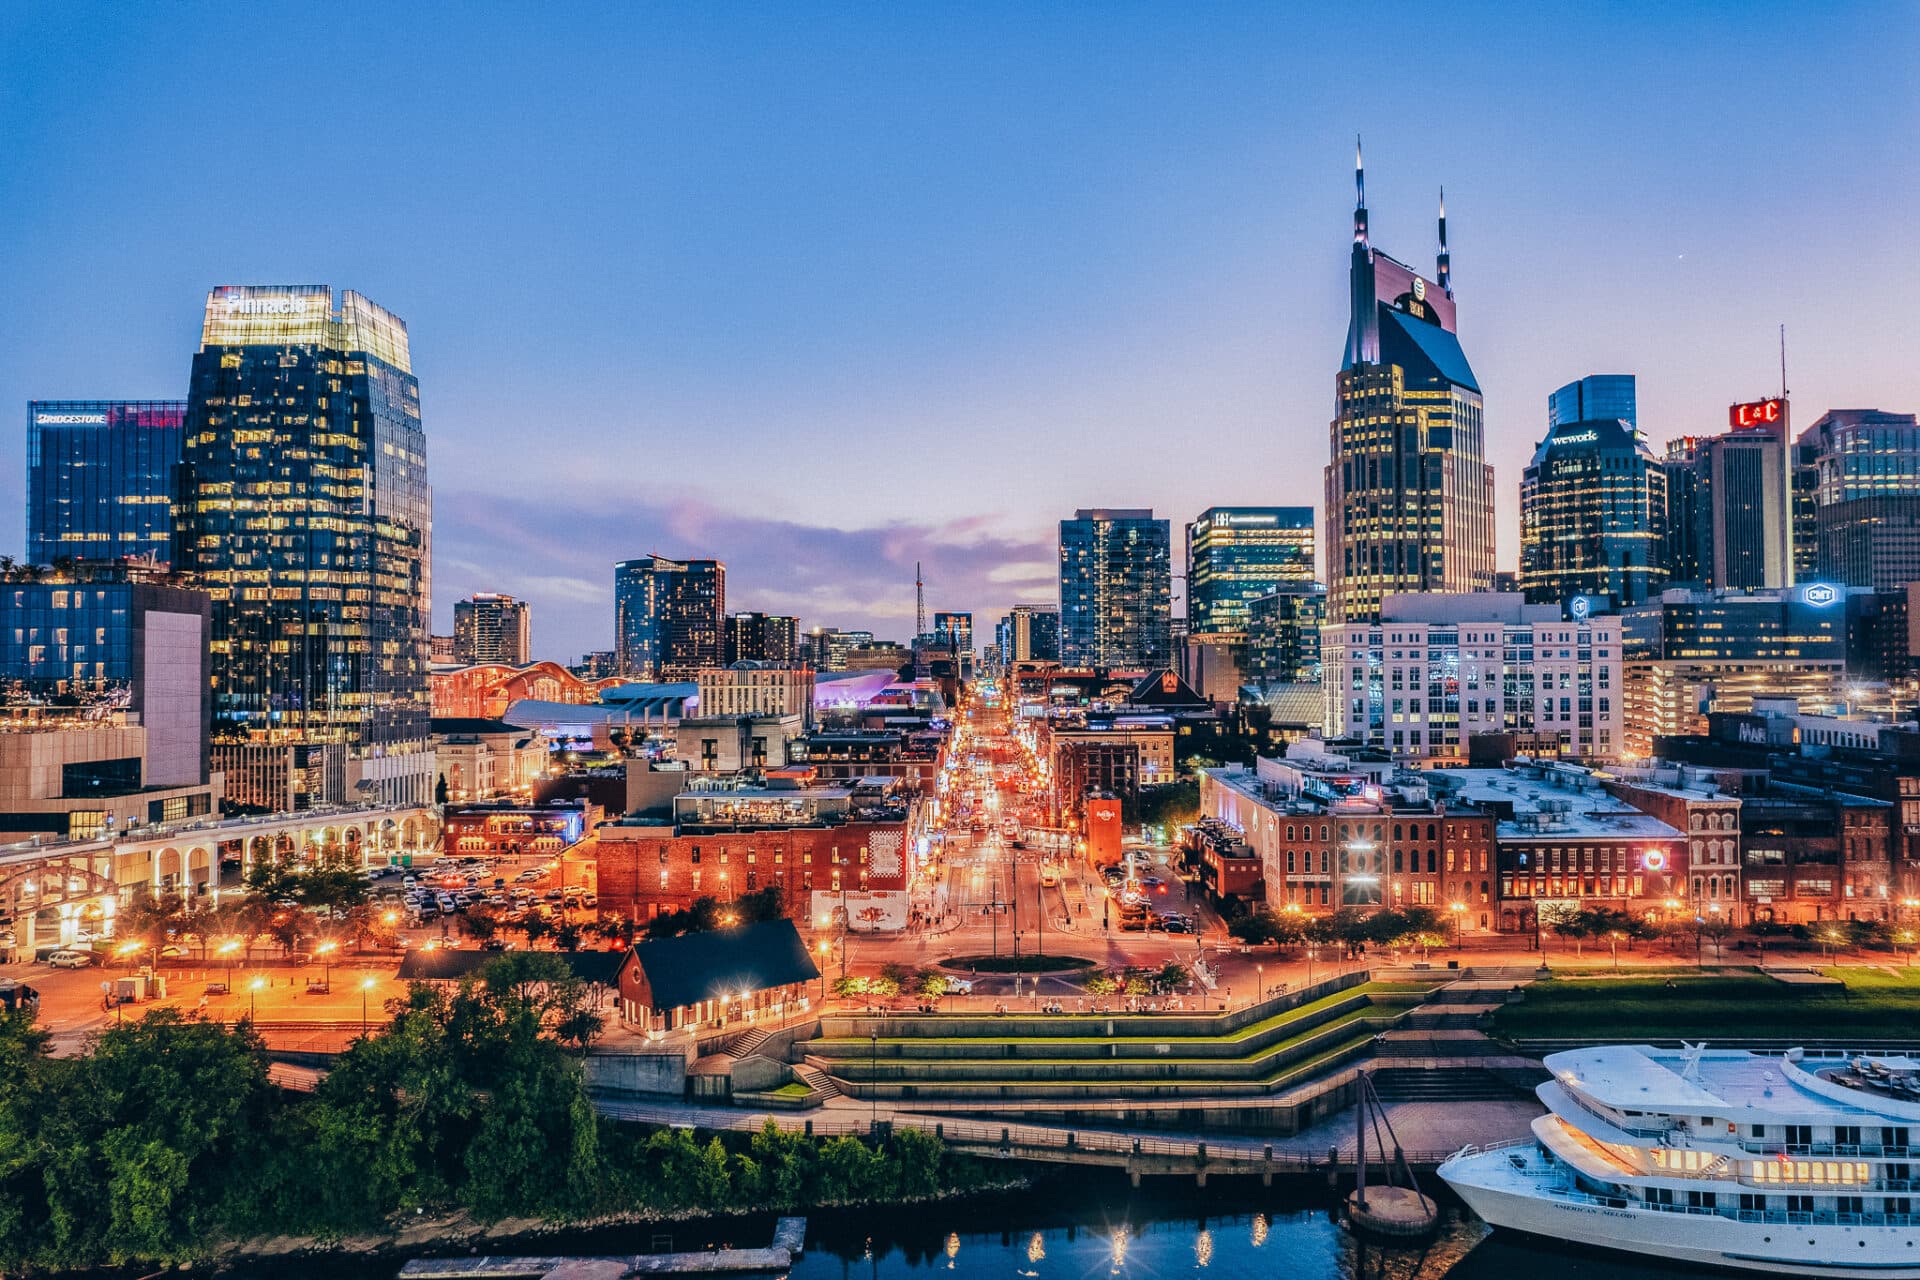
Nashville Industrial Vacancy Climbs to 7.30% as Supply Outpaces Tenant Demand
Nashville’s industrial market entered the second half of 2026 with a widening gap between what developers are building and what tenants are taking. Vacancy reached 7.30% in Q2 2026 as the market delivered 2.5 million square feet against just 137,000 square feet of net absorption — a shortfall of roughly 2.4 million square feet in a single quarter. Another 9.2 million square feet remains under construction, more than 90% of it still available for lease. Capital markets tell a different story: industrial sales volume hit $307 million at an average of $126 per square foot, with cap rates compressing to 6.10% as institutional buyers continued underwriting Nashville’s long-term growth. Asking rents held at $11.70 per square foot, up 4.90% year-over-year and among the highest in the Southeast, though elevated supply is expected to keep rent gains below historical norms into 2027.
Key Findings
- Vacancy rose to 7.30% on a supply-demand mismatch: Nashville delivered 2.5 million square feet in Q2 2026 but absorbed only 137,000 square feet. Speculative construction continues to outpace tenant uptake.
- The pipeline remains heavy at 9.2 million square feet: More than 90% of space under construction is still available for lease, giving tenants leverage and pressuring landlords toward concessions.
- Rents reached $11.70/SF, up 4.90% year-over-year: Nashville remains among the priciest industrial markets in the Southeast, but rent growth has decelerated sharply from its 2023 peak.
- Investment sales stayed resilient at $307 million: Average pricing of $126 per square foot and cap rate compression to 6.10% signal that investor conviction has not followed leasing fundamentals downward.
- Small-bay space is the market’s tightest segment: Buildings under 50,000 square feet continue to post strong absorption with vacancy well below the market average, and remain undersupplied.
- Construction is concentrated in the east: The East / I-40 & I-24 submarket holds 8.0 million of the metro’s 9.2 million square feet under construction — roughly 87% of the pipeline — alongside the market’s highest vacancy at 8.8%.
- Submarket rents span a 46% premium: The space-constrained Central/West core commands $14.77 per square foot while the North submarket’s large logistics inventory leases at $10.08.
- Population growth underwrites the demand case: The 14-county Nashville metro has grown roughly 30% since 2010 to 2,213,880 residents, with 3.0% unemployment against a 4.3% national average.
Nashville Industrial Market Overview
Nashville closed the second quarter of 2026 with industrial vacancy at 7.30% and average asking rent at $11.70 per square foot. The headline that matters is not the vacancy level itself — it is the mechanism behind it.
The market delivered 2.5 million square feet during the quarter and absorbed 137,000. That is a gap of roughly 2.4 million square feet of new space arriving faster than tenants can take it. Vacancy has climbed steadily as a result, well above the levels Nashville industrial held in 2020 and 2021.
Demand has not disappeared. It has become selective. Buildings under 50,000 square feet continue to post strong absorption with vacancy well below the market average, and small-bay product remains structurally undersupplied. Large logistics facilities absorb more slowly — even as Geodis, Under Armour, Nissan, and Starbucks keep signing leases in the market. The bifurcation is by size, not by tenant appetite.
Investment sales have decoupled from leasing. Volume reached $307 million in Q2 2026 at $126 per square foot, with cap rates compressing to 6.10%. Buyers are underwriting through the current supply cycle to Nashville’s demographic and logistics fundamentals, and pricing reflects that — the same conviction visible in the metro’s multifamily market, where pricing has held near its 2022 peak.
Nashville Industrial Rents
Asking rents in Nashville averaged $11.70 per square foot in Q2 2026, up 4.90% year-over-year. That keeps Nashville among the priciest industrial markets in the Southeast, but the trajectory has flattened considerably: rents have risen from $9.25 in 2022 to $11.70 in 2026, a cumulative gain of roughly 26%, while annual growth has cooled from a near-12% peak in 2023 to today’s 4.90%.
With more than 90% of the construction pipeline still available for lease, landlords face growing pressure to offer concessions. Rent growth is expected to stay below historical norms through 2027 as the market works through existing supply.
Asking Rent by Submarket
Rents vary sharply by submarket and building type, and the spread reflects the availability of space rather than location quality alone. The space-constrained Central/West core commands $14.77 per square foot — a 46% premium over the North submarket’s $10.08, where large logistics inventory dominates. Southwest sits at $12.62 and East / I-40 & I-24 at $11.35.
Rent growth runs almost inversely to rent level. Central/West, the most expensive submarket, posted the weakest growth at 2.5%. North led at 6.9%, with East / I-40 & I-24 and Southwest both at 6.0%. The pattern suggests the lower-priced logistics submarkets still have room to push rates, while the premium core is closer to its ceiling.
Nashville Industrial Vacancy
Vacancy Rate
Nashville’s industrial vacancy rate was 7.30% in Q2 2026, driven by a wave of speculative construction that continues to outpace tenant absorption. The market delivered 2.5 million square feet during the quarter but absorbed only 137,000 square feet.
The direction matters as much as the level. With 9.2 million square feet under construction and more than 90% of it unleased, further vacancy pressure is likely before the pipeline clears.
Vacancy by Submarket
The spread across Nashville submarkets is 320 basis points. North posted the lowest vacancy at 5.6%, followed by Central/West at 6.2% and Southwest at 6.9%. East / I-40 & I-24 carried the metro’s highest vacancy at 8.8%.
The East submarket is where the market’s risk concentrates. It combines the highest vacancy in the metro with 8.0 million square feet under construction — roughly 87% of the entire Nashville pipeline. It was also the strongest absorber in the quarter at 294,000 square feet. Southwest, by contrast, gave back 283,000 square feet of occupancy and North gave back 7,000, while Central/West added 15,000.
Nashville Industrial Construction
Under Construction and Deliveries
Nashville had 9.2 million square feet under construction in Q2 2026 after delivering 2.5 million square feet during the quarter. Developers are pushing toward newer, higher-spec facilities — a flight-to-quality pipeline aimed at tenants upgrading out of older stock.
The pipeline has stayed remarkably consistent in size. Under-construction volume measured 10.6 million square feet in 2022, dipped to 5.9 million in 2024, and has since rebuilt to 9.4 million in 2025 and 9.2 million year-to-date in 2026. Construction starts have moved in a wider band: 8.9 million square feet in 2022, a cycle low of 5.2 million in 2024, 8.4 million in 2025, and 5.8 million year-to-date in 2026.
Geographically, the building is concentrated. Wilson County and Southeast Nashville account for more than 80% of all deliveries since 2020. Notable projects include Cornerstone Business Park in Smyrna, Central Pike Logistics Center in Lebanon, and Prologis’s 3 million-plus square foot Mountain View Park. Small-bay space under 50,000 square feet remains undersupplied — the pipeline is not addressing the segment where demand is strongest.
Construction by Submarket
The pipeline is almost entirely one submarket. East / I-40 & I-24 holds 8.0 million square feet under construction. North has 357,000 square feet, Southwest 40,000, and Central/West has none at all — zero square feet under construction in the metro’s highest-rent submarket.
That concentration is the single most important structural fact in this report. It means Nashville’s vacancy trajectory over the next 18 months is largely a question about lease-up in one corridor, and it explains why the Central/West core can hold $14.77 rents while the metro average softens. Where there is no new supply, pricing holds.
Nashville Industrial Investment Sales
Industrial investment sales in Nashville reached $307 million in Q2 2026 at average pricing of $126 per square foot — implying roughly 2.4 million square feet traded during the quarter — with cap rates compressing to 6.10%. That underscores continued investor confidence even as leasing fundamentals have softened.
REITs, institutional buyers, and private capital all remain active. The draw is Nashville’s population growth and a logistics position that reaches more than half the U.S. population within a day’s drive. Cap rates have swung through a wide band over the past decade, and the current 6.10% sits well inside that range.
Significant Sale Comps
The largest of the quarter’s significant comps was 501 Hixson Blvd in Lebanon: 290,860 square feet at $31.29 million, or $107.59 per square foot. It was followed by 1040 Turkey Creek Rd in Dickson at $30.86 million for 300,891 square feet ($102.57/SF).
The most instructive comp is 640 Massman Dr in Nashville — 169,855 square feet at $24.93 million, or $146.77 per square foot, on a 5.00% cap rate. That is the only cap rate disclosed in the comp set and a 16% premium to the market’s $126 average price per square foot, paid for infill location. The report separately highlights Stos Partners’ $25 million acquisition of a 170,000 square foot facility near the airport at a 5% cap rate. Airport-adjacent product is trading on a different basis than the outer-county logistics boxes.
The rest of the set: 994 Hixson Blvd in Lebanon at $22.21 million ($110.45/SF), 2008 Johnson Industrial Blvd in Nolensville at $10.5 million ($131.25/SF), and 214 Fountain Head Rd in Portland at $5.6 million ($27.91/SF).
Submarket pricing follows the same infill logic. Central/West product traded at $170 per square foot against North at $68 — a two-and-a-half-times spread — with East / I-40 & I-24 at $134 and Southwest at $109. Cap rates ran inversely: 6.4% in Central/West and East, 6.5% in Southwest, and 7.6% in North.
The Nashville Economy and Industrial Demand
Nashville, Tennessee’s capital and largest city, anchors a 14-county metro of more than 2.2 million residents and remains one of the fastest-growing large metros in the country, with population up roughly 30% since 2010. Growth has moderated recently — from 2.3% year-over-year in 2021 to 0.7% in 2026 — but the base has expanded from 1.99 million residents in 2020 to 2.21 million today.
The metro’s 3.0% unemployment rate runs well below the 4.3% national average, and its $93,036 median household income outpaces the $85,118 U.S. figure. Households total 900,420.
Healthcare is the cornerstone industry, supporting more than 330,000 jobs and an estimated $68 billion in annual economic impact through anchors including HCA Healthcare and Vanderbilt University Medical Center. Corporate relocations continue to fuel momentum — most notably Oracle’s $1.35 billion world headquarters targeting 8,500 new workers by 2031, alongside Amazon and AllianceBernstein.
That same population and income growth is reshaping demand across property types in the metro, including Nashville retail.
For industrial demand, the relevant read is the combination of household formation, above-average incomes, and a distribution position covering half the U.S. population within a day’s drive. Those fundamentals are what buyers are paying 6.10% cap rates to access, and they are unchanged by a single quarter of soft absorption.
Nashville Industrial Outlook
Elevated supply is expected to keep rent gains below historical norms into 2027. With more than 90% of the 9.2 million square foot pipeline still available for lease, the near-term balance of power sits with tenants — particularly in the East / I-40 & I-24 corridor, where 8.0 million square feet is under construction against 8.8% vacancy.
Three positions follow from the data. Tenants seeking large logistics space have the strongest negotiating leverage in the East submarket and should expect meaningful concession packages. Tenants seeking small-bay space under 50,000 square feet will find the opposite — that segment is undersupplied, the pipeline is not addressing it, and rates should hold. Investors continue to price Nashville on its demographic and logistics fundamentals rather than current occupancy, and the Central/West core, with zero square feet under construction, offers the cleanest supply picture in the metro.
Nashville Industrial by the Numbers — Q2 2026
- Vacancy Rate: 7.30%
- Average Asking Rent: $11.70/SF
- Annual Rent Growth: 4.90%
- Net Absorption: 137,000 SF
- SF Delivered (Q2): 2.5M SF
- SF Under Construction: 9.2M SF
- Construction Starts (YTD 2026): 5.8M SF
- Sales Volume: $307M
- Average Price Per SF: $126
- Average Cap Rate: 6.10%
- Lowest Submarket Vacancy: North, 5.6%
- Highest Submarket Vacancy: East / I-40 & I-24, 8.8%
- Highest Submarket Rent: Central/West, $14.77/SF
- Lowest Submarket Rent: North, $10.08/SF
- Strongest Submarket Rent Growth: North, 6.9%
- Largest Submarket Pipeline: East / I-40 & I-24, 8.0M SF
- Largest Sale: 501 Hixson Blvd, Lebanon — $31,292,281 (290,860 SF)
- Tightest Cap Rate Comp: 640 Massman Dr, Nashville — 5.00%
- Metro Population: 2,213,880
- Households: 900,420
- Median Household Income: $93,036
- Unemployment: 3.0%
Frequently Asked Questions
What is the industrial vacancy rate in Nashville, TN?
The Nashville industrial vacancy rate was 7.30% in Q2 2026. Vacancy rose because speculative construction outpaced tenant absorption — the market delivered 2.5 million square feet during the quarter but absorbed only 137,000 square feet.
What is the average industrial rent in Nashville?
Average industrial asking rent in Nashville was $11.70 per square foot in Q2 2026, up 4.90% year-over-year. That keeps Nashville among the priciest industrial markets in the Southeast. Rents range from $10.08 per square foot in the North submarket to $14.77 in the Central/West core.
How much industrial space is under construction in Nashville?
Nashville had 9.2 million square feet of industrial space under construction in Q2 2026, with more than 90% of it still available for lease. Roughly 8.0 million square feet of that total sits in the East / I-40 & I-24 submarket. Construction starts year-to-date in 2026 totaled 5.8 million square feet, down from 8.4 million in 2025.
What are Nashville industrial cap rates in 2026?
The average Nashville industrial cap rate was 6.10% in Q2 2026. By submarket, cap rates ran 6.4% in Central/West and East / I-40 & I-24, 6.5% in Southwest, and 7.6% in North. The quarter’s tightest disclosed comp was 640 Massman Dr in Nashville at a 5.00% cap rate.
Is Nashville industrial real estate overbuilt?
In the large logistics segment, supply currently exceeds demand: 9.2 million square feet is under construction against quarterly absorption of 137,000 square feet, and more than 90% of the pipeline is unleased. Small-bay space under 50,000 square feet is the opposite — it remains undersupplied, with vacancy well below the market average and strong continued absorption.
Which Nashville submarket has the most industrial construction?
East / I-40 & I-24 holds 8.0 million square feet of the metro’s 9.2 million square feet under construction — roughly 87% of the Nashville pipeline. It also carries the metro’s highest vacancy at 8.8%. Central/West has no industrial space under construction at all.
How much industrial property sold in Nashville in Q2 2026?
Nashville industrial investment sales totaled $307 million in Q2 2026 at an average of $126 per square foot, implying roughly 2.4 million square feet traded. The largest disclosed transaction was 501 Hixson Blvd in Lebanon at $31.29 million for 290,860 square feet.
Why are investors still buying Nashville industrial despite rising vacancy?
Cap rates compressed to 6.10% even as leasing fundamentals softened because buyers are underwriting Nashville’s long-term fundamentals rather than current occupancy. The metro has grown roughly 30% since 2010 to 2.2 million residents, unemployment is 3.0% against a 4.3% national average, and the market reaches more than half the U.S. population within a day’s drive.
What is driving industrial demand in Nashville?
Population growth and corporate relocation are the primary drivers. The 14-county metro has added more than 200,000 residents since 2020. Healthcare anchors the economy with over 330,000 jobs and $68 billion in annual impact through HCA Healthcare and Vanderbilt University Medical Center, while Oracle’s $1.35 billion headquarters targets 8,500 new workers by 2031. Active industrial tenants include Geodis, Under Armour, Nissan, and Starbucks.
What is the outlook for Nashville industrial rents?
Rent growth is expected to stay below historical norms through 2027. With more than 90% of the 9.2 million square foot construction pipeline still available for lease, landlords face growing pressure to offer concessions, particularly for large logistics space in the East / I-40 & I-24 corridor.
For more quarterly market data across property types and markets, visit Matthews™ Insights.